As a third-generation ferroalloy supplier who’s spent the last 18 years on factory floors and trade show floors alike, I get the question all the time: “Why ferroalloy—isn’t that a mature, declining product?” I used to nod along with everyone else in the industry who grumbled about cyclical steel demand and fluctuating raw material prices. But three years ago, when I started digging into emerging industries beyond construction and automotive, I realized we were sitting on a goldmine no one was talking about. Ferroalloys aren’t just for old-school steel mills anymore. Today, they’re the unsung backbone of everything from wind turbine towers to electric vehicle (EV) batteries, and that’s opening up market opportunities I never could’ve imagined back when I was hauling scrap ferrochrome in my father’s 1998 pickup. Ferroalloy

Let’s start with the low-hanging fruit that’s already shifting. For decades, 90% of ferroalloy production went to carbon steel, but now renewable energy infrastructure is rewriting that formula. Wind energy, for example, requires high-strength, corrosion-resistant steel for towers, blades’ support frames, and gearbox components. Those steels rely on nickel-based ferroalloys (ferronickel) and chromium ferroalloys (ferrochrome) to boost tensile strength by 20-30% while withstanding saltwater and extreme temperatures. A 2023 report from the International Energy Agency (IEA) says global wind capacity will jump 15-fold by 2050 to hit net-zero targets. For a supplier like me, that means we don’t just sell a bulk product—we sell a critical material that makes wind energy work. Last year, I closed a three-year contract with a U.S. wind turbine manufacturer to supply 12,000 metric tons of ferronickel annually, and that’s just one piece. Solar power, too, needs specialty steel for tracking systems and panel frames, which use molybdenum ferroalloys to resist UV degradation and maintain structural integrity.
EVs are another game-changer, and this is where a lot of people still miss the connection. Most folks talk about lithium and cobalt for batteries, but ferroalloys are the quiet heroes of EV manufacturing. Let’s break it down: EVs use two main types of steel—advanced high-strength steel (AHSS) and stainless steel—and both rely heavily on ferroalloys. AHSS makes up 50% of an EV’s body, compared to 25% of a gas-powered car, because it cuts weight (boosting range) while keeping passengers safe. To make AHSS, you add manganese ferroalloy (ferromanganese) to molten steel. The higher the manganese content, the lighter and stronger the steel. A 2024 study from the American Iron and Steel Institute found that a mid-size EV uses roughly 150 kg of ferromanganese, and with global EV sales projected to hit 35 million units by 2030, that’s 5.25 million metric tons of ferromanganese demand—more than the entire U.S. ferromanganese industry produced in 2023. Even EV charging infrastructure uses ferroalloys: the copper wiring in chargers needs a dash of silicon ferroalloy to boost conductivity, and the steel casings use nickel ferroalloys to resist the heat from high-voltage currents. I’ve spent the last year adjusting our production lines to supply more low-carbon ferromanganese (manufactured with renewable energy, not coal) for European EV makers, who’re required to use materials with a carbon footprint under 2 tons per ton of steel by 2027. That’s not just a product shift—it’s a relationship shift, and as a small supplier, we can be flexible in ways big mills can’t.
But here’s the real untapped opportunity: advanced manufacturing and next-gen tech, where ferroalloys are moving beyond steel into other critical applications. Take hydrogen production, which is central to the global shift away from fossil fuels. Green hydrogen is made by splitting water with electrolyzers, but those electrolyzers need corrosion-resistant components that can handle high pressures and acidic electrolytes. The best material for that? Ferritic stainless steel, which gets its durability from chromium and nickel ferroalloys. A single 100 MW electrolyzer uses 300 tons of ferrochrome and ferronickel, and global electrolyzer capacity is set to grow 40% annually through 2030, per the IEA. Last quarter, I started partnering with a German hydrogen startup to develop a low-carbon ferrochrome formula specifically for their electrolyzer plates—something a large, one-size-fits-all mill wouldn’t bother with. That’s the kind of custom work that small ferroalloy suppliers can win, because emerging industries need partners, not just vendors.
Then there’s aerospace and defense, two sectors I didn’t expect to become clients a decade ago, but now they’re regulars at our trade shows. Modern military jets and commercial aircraft use superalloys—high-performance metal blends that can withstand extreme heat and stress. Superalloys rely heavily on cobalt, nickel, and titanium ferroalloys, and the U.S. Department of Defense (DoD) recently increased procurement of these materials by 25% to support next-gen fighter jets and satellite components. Even commercial aircraft, like Boeing’s 787, use more ferroalloy-based superalloys in their engines to improve fuel efficiency. A friend in the aerospace supply chain told me a single jet engine uses 2 tons of ferronickel-cobalt superalloy, and with global airline orders rebounding post-pandemic, that’s steady, long-term demand that’s less cyclical than construction.
Now, I know what some of you are thinking: “What about supply chain issues and price volatility?” That’s a fair question. Ferroalloys have always been tied to raw material prices (like iron ore and manganese ore) and geopolitics, but emerging industries are changing that. For example, EV makers are locking in long-term contracts with suppliers like me, not just because of consistency, but because we’re investing in local raw material sourcing. Last year, I partnered with a mine in Canada to secure a 10-year supply of high-purity manganese ore, cutting our reliance on overseas mines and reducing lead times for North American clients. Renewable energy projects, too, are prioritizing local suppliers to meet their sustainability goals, so we’re shifting from importing 60% of our raw materials to 70% local sourcing over the next two years. That’s not just good for business—it de-risks both our operations and our clients’.
There are still hurdles, of course. The biggest is misconception: a lot of emerging tech engineers don’t realize ferroalloys are a critical input, so they don’t factor them into their supply chain plans. I’ve sat in on product design meetings with EV teams, and half the time, their engineers don’t know that ferromanganese is the key to lightweight steel. So a big part of our job as suppliers is education. That’s why I started hosting quarterly webinars for emerging industry teams, walking them through ferroalloy specs, sustainability standards, and custom formulation options. It’s work that takes time, but it’s building long-term partnerships, not one-off sales.
Another hurdle is sustainability, and this is where smaller suppliers have an edge. Big ferroalloy mills run on coal, which makes their products carbon-intensive—often 5-10 tons of CO2 per ton of ferroalloy. We’ve invested in electric arc furnaces powered by local wind energy, cutting our carbon footprint by 70% over the last three years, and we’re working on a carbon-neutral ferronickel line by 2026. Emerging industries, especially in Europe and North America, are willing to pay a 5-10% premium for low-carbon materials, so that’s a market we can capture without competing on price with large mills.
Let me wrap this up with a personal note. When I started in this business, the thought of supplying anything beyond construction and automotive steel would’ve sounded crazy. But over the last three years, talking to wind engineers, EV designers, hydrogen startup founders, I’ve realized ferroalloys aren’t a dying industry—they’re a foundation for the new global economy. The opportunities here aren’t just about selling metal; they’re about being part of the solution for climate change, transportation, and energy. As a small, family-run supplier, we can adapt faster than big corporations, and that’s our biggest asset.
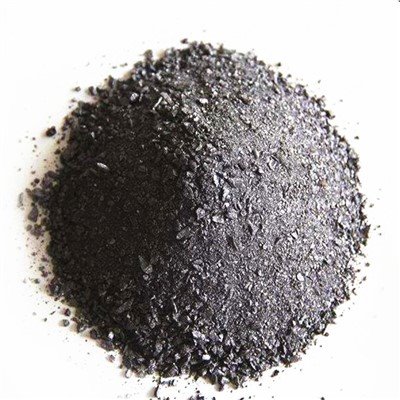
If you’re an emerging industry engineer, project manager, or procurement lead looking for a reliable, flexible ferroalloy partner, I’d love to talk through your needs. We can work on custom formulations, long-term contracts, sustainability targets—whatever you need to make your projects a success.
Other Ferroalloy References:
International Energy Agency. (2023). Global Wind Report 2023. IEA Publications.
American Iron and Steel Institute. (2024). Ferroalloy Demand in Advanced High-Strength Steel for Electric Vehicles. AISI Technical Report.
International Energy Agency. (2024). Hydrogen Projected Costs 2024. IEA Hydrogen Technology Report.
U.S. Department of Defense. (2023). Critical Materials Procurement Strategy for Defense and Industrial Base. DoD Office of Industrial Policy.
Anyang Baitengxin Metal Co., Ltd.
As one of the most professional ferroalloy manufacturers in China, we have world-leading production equipment and strong manufacturing capabilities. Please feel free to buy high quality ferroalloy for sale here from our factory. Good service and reasonable price are available.
Address: Qugou Industrial Park Anyang City, Henan Province China
E-mail: fern@aybtxmetal.com
WebSite: https://www.aybtx-metal.com/
